How to Build a Personal Financial Safety Margin When Income Is Uncertain
A personal financial safety margin gives you room to respond when income changes, expenses rise or an unexpected obligation appears. It is not a promise that every emergency will be easy. It is a practical reserve of cash, lower commitments and better information that reduces the pressure to make desperate decisions.
Many people think financial progress begins only when income becomes large. Yet stability often starts earlier. It begins when you understand what must be paid, separate essentials from preferences and deliberately create space between what comes in and what goes out.
For Christians, this is an expression of stewardship rather than fear. Wisdom prepares for foreseeable needs while continuing to trust God. The goal is not to place faith in money. It is to manage available resources responsibly so that a difficult month does not immediately become a crisis.
What Is a Personal Financial Safety Margin?
A personal financial safety margin is the financial space created by accessible savings, controlled commitments, realistic planning and reliable information. It helps you absorb a disruption without immediately borrowing, missing essential payments or abandoning important responsibilities.
The margin may begin with a modest amount. Its value is not measured only by size. It is also measured by what it allows you to do. Even a small reserve can cover transport, electricity, food or an urgent communication cost while you reorganise.
A safety margin is broader than an emergency fund. Savings are central, but the margin also includes unused borrowing capacity, expenses that can be reduced, accurate records and a plan for responding to income changes.
Begin With the Cost of One Essential Month
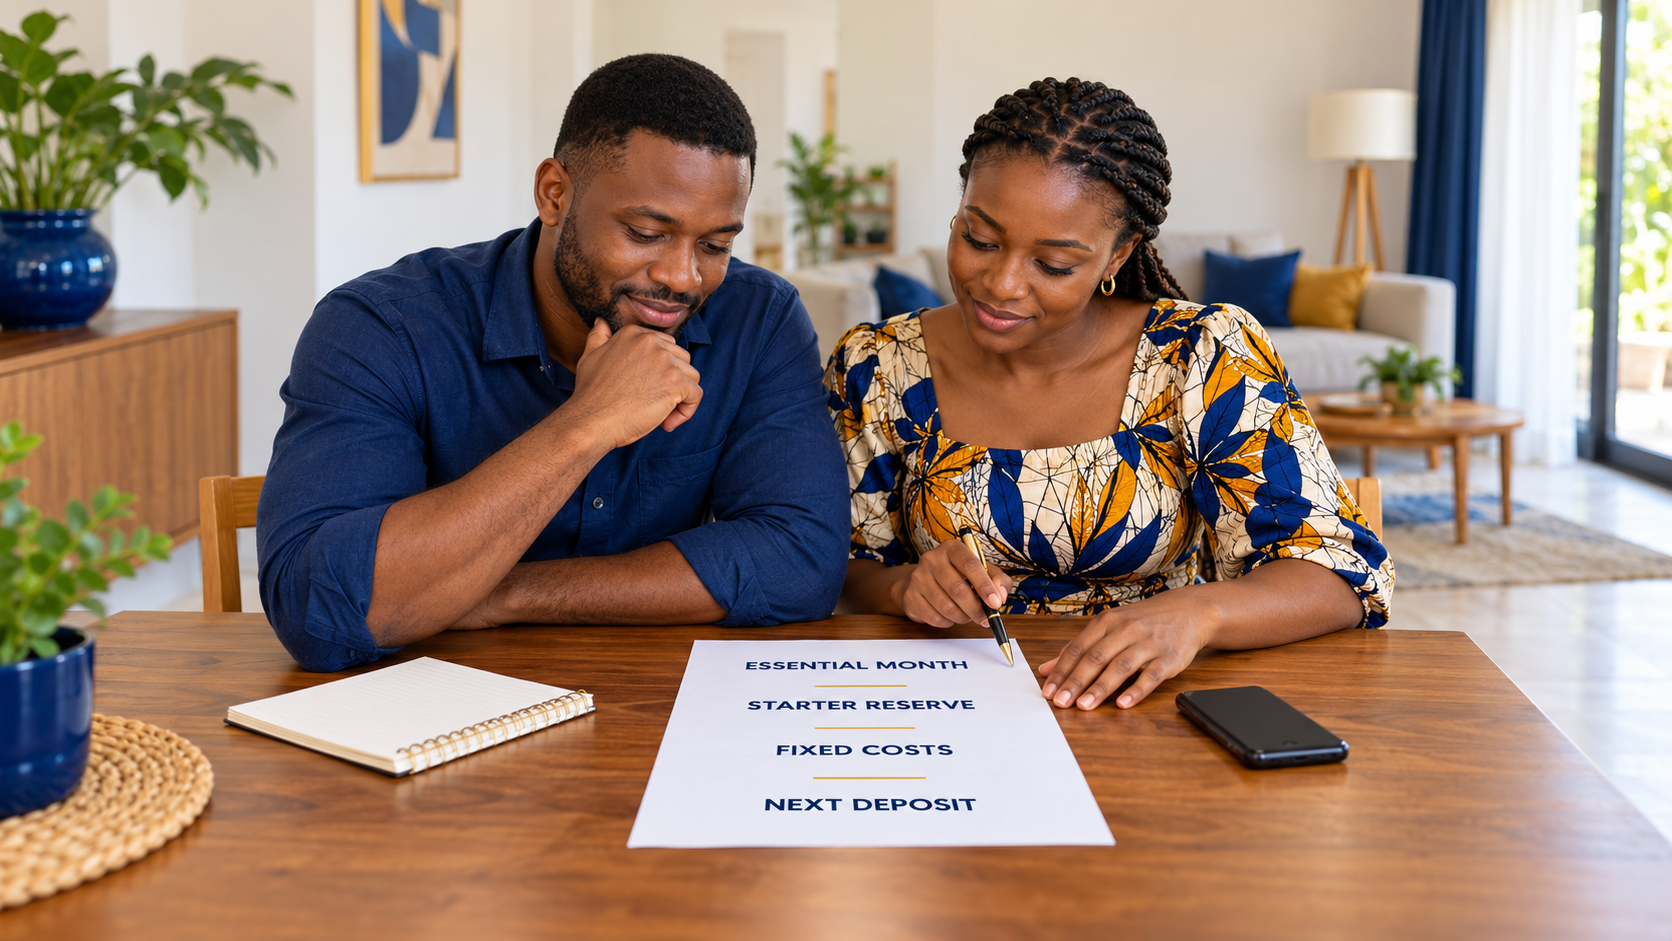
Before choosing a savings target, calculate the minimum cost of keeping your household functioning for one month. Include essential housing, food, utilities, transport, medication, communication, insurance and unavoidable debt payments. Exclude expenses that could pause during a genuine disruption.
This figure is not your normal lifestyle budget. It is your essential-month number. It tells you how much protection one month of reserves would provide and gives you a practical starting point.
For example, suppose normal monthly spending is E12,000 but essential commitments total E7,500. Your first safety-margin target is not automatically E12,000. A staged target based on E7,500 may be more realistic and motivating.
Build the Margin in Practical Stages
A large target can make saving feel impossible. Divide the journey into stages. First, build a starter reserve for common disruptions. Next, aim for one essential month. After that, work gradually toward several months if your circumstances require it.
Someone with irregular income may need a larger margin than a person with stable employment and strong benefits. A self-employed person may also need separate business reserves. The appropriate target depends on income stability, dependants, health needs, insurance, debt and access to support.
Do not wait for a perfect month. Choose a realistic amount or percentage and transfer it consistently. Small deposits made repeatedly create both money and discipline.
Create Your Personal Financial Safety Margin Before Spending Expands
When income increases, spending often expands quickly. New subscriptions, repayments and lifestyle commitments absorb the improvement before it creates stability. Decide in advance what portion of any increase, bonus or irregular payment will strengthen your personal financial safety margin.
This does not mean refusing every enjoyment. It means giving new income a purpose before it disappears. You may divide extra money among immediate obligations, reserves, planned goals and responsible giving.
Automating the transfer can help. However, automation does not replace review. Check that the amount remains affordable and that the reserve is held somewhere accessible enough for emergencies but separate enough to reduce casual spending.
Reduce Fixed Commitments That Remove Your Flexibility
Savings are only one side of the margin. The other side is the amount you are required to pay each month. High fixed commitments can make a reasonable income feel fragile.
Review contracts, instalments, subscriptions, recurring transfers and debt payments. Ask which commitments are essential, which remain valuable and which continue only because they have not been reviewed.
Cancelling wasteful costs does not create lasting improvement unless the released money is redirected. Move part of the saving into your reserve or use it to reduce expensive debt. Otherwise, another expense may simply take its place.
Use Separate Reserves for Predictable Irregular Costs
Not every large expense is an emergency. School costs, annual licences, vehicle servicing, celebrations and seasonal travel may occur irregularly, but many are predictable. Treating them as emergencies repeatedly weakens your reserve.
Create sinking funds for these costs. Estimate the amount and divide it by the number of months before payment. This keeps the personal financial safety margin available for genuine disruption rather than routine expenses that arrived on schedule.
Protect the Margin With Clear Rules
Write down when the reserve may be used. Suitable reasons could include essential expenses after income loss, urgent health needs, critical repairs or unavoidable family responsibilities. A sale, social invitation or attractive investment opportunity is not automatically an emergency.
Also decide how you will rebuild the reserve after using it. The first goal after the crisis may be to restore stability, not to return immediately to normal discretionary spending.
Clear rules reduce emotional decision-making. They also make it easier for couples or families to discuss whether a withdrawal is necessary.
Keep Your Financial Information Current
A reserve cannot protect you fully if you do not know what is happening. Review income received, essential payments, debt balances, upcoming obligations and reserve levels at least monthly.
Irregular earners may need a weekly review. When income arrives, allocate it according to priority instead of assuming another payment will come soon. Separate money needed for taxes or business costs from personal funds.
Accurate information helps you respond early. You can reduce spending when income starts weakening rather than waiting until accounts are empty.
Combine Faith With Responsible Financial Preparation
Biblical stewardship does not require anxiety about every possible future event. It does encourage wisdom, diligence and honest planning. Proverbs 21:5 teaches that diligent planning leads toward plenty, while haste leads toward poverty.
Preparation should not become hoarding or a refusal to help others. Nor should generosity ignore legitimate household obligations. Faithful stewardship seeks wisdom about saving, giving, spending and responsibility.
Pray for provision and direction. Then review the numbers, correct avoidable leakage and take the next practical step. Trust and disciplined action can work together.
A Seven-Day Safety-Margin Starter Plan
- Calculate your essential-month number.
- Choose a modest starter-reserve target.
- Open or identify a separate place for the reserve.
- Review recurring commitments and cancel one unnecessary cost.
- Create one sinking fund for a predictable expense.
- Write clear rules for using and rebuilding the reserve.
- Schedule a monthly financial review.
This plan will not solve every financial challenge in one week. It will, however, turn a general desire for security into visible action.
Conclusion: Create Room for Wiser Decisions
A personal financial safety margin is not about reaching a perfect number before you can feel secure. It is about creating more room between a financial disruption and a damaging response.
Begin with your essential-month cost. Build in stages, control fixed commitments, separate predictable costs and keep your records current. If you use the reserve, rebuild it deliberately.
Financial freedom develops through repeated responsible choices. Start with the amount available today, and continue strengthening the margin that will help you act with greater calm, wisdom and faith tomorrow.
Continue Your Financial-Freedom Journey
A Guide to Financial Freedom and Independence
This catalogue-verified resource supports readers who want to develop broader habits for financial freedom and independence. No price, format, rating, review, sales or royalty claim is made.
Continue Learning With Freedom Hub
Take the First Practical Step
Calculate the minimum cost of one essential month. Then choose the first amount you will place into your reserve.
Explore more practical guidance in the Freedom Hub Knowledge Centre .